India’s Unified Payments Interface (UPI) has transformed the way people make and receive payments. It now accounts for 85% of India’s digital payment transactions by volume (Press Information Bureau, 2026). But the rapid expansion of digital payments has not translated into equal use by women and men.
This matters for financial inclusion. A bank account connects a woman to the formal financial system, but digital payments can shape what that access means in practice: whether she can receive money, pay bills, transfer funds, check balances, or avoid repeated trips to the bank. When account ownership is nearly universal and digital payment use remains much lower, the remaining gap is not simply one of access.
Our study in Telangana illustrates this gap clearly. Nearly 99% of women in our sample had a bank account and 85% used a mobile phone, yet only about 33% reported using UPI, compared with 64% of men. Women were also less likely than men to own the phones they used and to own smartphones.
We set out to understand what helps women move from access to using digital payments. We combined a household survey of 2,820 households across Adilabad, Bhadradri Kothagudem, Jayashankar Bhupalpally, and Hyderabad with qualitative research in Bhadradri Kothagudem, Jayashankar Bhupalpally, and Hyderabad. The qualitative work included women, their spouses, Digital Budget Ranis (DBRs), self-help group (SHG) and village organization leaders, Community Resource Persons (CRPs), Bank Mitras, merchants, and other community actors.
In this blog, we look at four factors that help explain the distance between access and meaningful use: capability and confidence, trusted support, opportunities for regular use, and autonomy.
Small transactions can build capability and confidence
For some women, familiarity with UPI came from watching someone else use it rather than from completing a transaction themselves. They had seen a husband scan a QR code or a child send money, but making a payment on their own could still feel risky. Fear of sending the wrong amount or transferring money to the wrong person was common in our interviews.
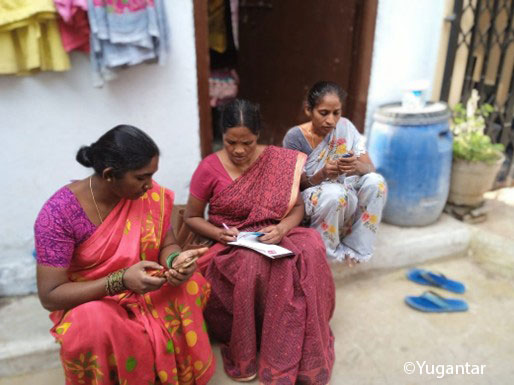
Yugantar’s Digital Budget Rani program gave women hands-on practice with UPI. The training included a practical exercise in which participants completed a ₹1 transfer. For some women, starting with such a small amount made the first transaction feel manageable.
I was initially afraid of sending one rupee, but was eventually convinced by my sister, as it was only one rupee. And then, once I received it back, I felt relieved.
Other women described checking transaction details carefully, keeping proof of payments, or asking someone to watch while they attempted an early transaction. These low-risk first steps mattered because they allowed women to practice without feeling that a large amount of money was at stake.
Training also appears relevant to the move from awareness to use. In our analysis of comparable rural SHG women, training was associated with a 9.4 percentage-point higher probability of UPI use. The qualitative interviews suggest that hands-on practice, reassurance, and continued support can help women build confidence beyond the first transaction.
SHG membership offered another route to building women's confidence. Membership and leadership roles gave women practical experience with banks, forms, loans, bookkeeping, and other financial responsibilities. For some women, these roles also expanded their confidence outside the household.
I think for the first time, I went outside and interacted with many people and got paid for this.
Trust often comes through people, not platforms
How women learned to use digital payments also mattered. Nearly 89% of women reported learning through family or friends, compared with 69% of men. Only about 12% of women reported learning independently, compared with 32% of men. In-app instructions and video explainers played a relatively small role for both women and men.
In the rural study districts, Yugantar’s training worked through CRPs connected to the Society for Elimination of Rural Poverty (SERP) and the SHG system. These were often people women already knew. Respondents repeatedly described familiarity and visible institutional backing as important sources of trust.
People find it difficult to trust. If we are from the collector's office, they will take us seriously because they will trust the government.
Trust continued to matter after onboarding. When transactions failed, or users were unsure what to do, women often approached SHG leaders, CRPs, DBRs, or family members first. Bank Mitras and banks also provided a route for account linking, KYC, onboarding, and problems that required formal resolution, though support was uneven. For many women, trusted people were therefore part of the infrastructure that made digital payments usable.
Regular use needs a reason
Knowing how to make a digital payment does not mean it will become part of everyday life. Women were more likely to value UPI when it solved a problem they already faced.
School-fee payments came up repeatedly in our interviews. Women described avoiding travel to school and waiting in queues to make time-bound payments, which could otherwise mean having to skip work. Others valued reducing bank visits, transferring money online, receiving money directly into their accounts, and having a record of a payment. In rural areas, fewer trips to the bank could also save bus fare and working hours.
For some women, being able to receive money was useful even if they did not make many outgoing payments. A Yugantar team member described women saying that receiving wages, bonuses, or other payments directly into their accounts was itself valuable.
Stree Nidhi loan repayments provide another example. In the settings we studied, repayments had shifted from cash to mandatory digital payments, creating a structured and recurring use case. The qualitative evidence suggests that repeated repayments gave women opportunities to practice digital transactions, check repayment status, and become more familiar with the process over time.
SHG contributions show the other side of this story. Although SHGs were central to women’s financial lives, 86.68% of women in our sample preferred to make their individual SHG contributions in cash, compared with 5.86% through UPI. In one group, the obstacle was not women’s willingness to use digital payments but the group’s own practice.
Members want to pay through UPI, but I won't accept. It is easy to keep track of the accounts with cash.
The contrast with Stree Nidhi is useful. Institutions can create repeated opportunities to practice digital payments, but they can also close those opportunities. At the same time, our interviews show that women did not necessarily want to replace cash altogether. They often treated cash and UPI as complementary, choosing between them depending on connectivity, distance, the type of transaction, and whether digital payments were accepted. Meaningful digital inclusion is therefore about expanding women’s options rather than simply moving every transaction online.
Knowing how is not the same as being allowed to
Perhaps the clearest distinction in our findings was between capability and control. Among women who used UPI, 90% said they could transact without assistance, yet 24% still reported needing permission to use it. Similarly, 75.76% of women knew how to withdraw money from a bank account, but 41.52% reported needing permission to do so. Knowing how to complete a financial task did not necessarily mean being free to do it.
Our interviews showed how this distinction played out inside households. A bank account or UPI application could formally belong to a woman while another family member effectively controlled it. Women sometimes relied on husbands or sons to make ATM withdrawals or operate UPI. In other cases, family members knew or controlled the PIN.
Most of the women’s accounts are already connected to either PhonePe or GPAY. The husbands use both apps: one connected to the wife's account and another to his. The wife’s salary or any income is directly debited to the account, but only the husband knows and uses it. She has no power over the money; she can't spend her money according to her wishes.
Control over credentials was especially important. Our qualitative research documented cases in which family members controlled women’s UPI PINs, changed them without their knowledge, or restricted access to applications. Technical capability could therefore coexist with limited financial autonomy.
Digital payments could also affect financial privacy in different ways. Some women valued being able to see balances and receive money directly into their own accounts. Others preferred keeping some savings in cash because digital transactions left a record that could be visible to family members with access to the account, device, or PIN. Whether digital payments strengthened women’s control depended partly on who controlled these resources.
What this adds up to
A woman may have a bank account in her name but have someone else operate it. She may have UPI installed but not control the PIN. She may know how to transact but still need permission to do so. Additionally, she may successfully make a first digital payment without having a reason, or the support, to make a second one.
This shifts the questions we should ask about women’s digital financial inclusion. Having an account is only the starting point. What matters is whether a woman can transact confidently and independently, whether she controls the device and PIN, whether she has useful reasons to keep using digital payments, and whether she knows where to turn when something goes wrong.
These findings are also relevant to the Viksit Bharat 2047 agenda. NITI Aayog’s DPI@2047 roadmap describes India’s digital public infrastructure as having driven "financial inclusion at population scale" and identifies UPI as a key part of that foundation. It argues that the next phase of India’s digital transformation should move beyond financial inclusion toward livelihood-led, productivity-driven growth. For women, our findings suggest that this next phase depends not only on digital services being available, but on whether they can be used regularly, confidently, and independently.
Our forthcoming blogs in this series will look more closely at these barriers and enablers, including safety and trust, training and handholding, gender norms and autonomy, and what they imply for the design of digital financial services and public policy.